Free public verification guide

Check before you pay, borrow or invest.

A registration number can look reassuring and still be the wrong type of registration. Use the official regulator for the activity being offered.

Illustrated guide to checking financial providers, credit providers and banks

Which registration should you check?

The answer depends on what the person or business is actually offering you.

FSP
FSCA

Financial Services Provider

Use this when someone is giving financial advice or providing an intermediary service relating to financial products, such as investments, insurance or other regulated financial products.

Check:Legal name · FSP number · authorisation status · the relevant product/category
Search the official FSCA register ↗
NCR
National Credit Regulator

Credit Provider

Use this when a business is offering you credit — for example a loan, store credit or another credit agreement regulated by the National Credit Act.

Check:Legal/trading name · NCRCP number · registration status
Search the official NCR register ↗
PA
SARB / Prudential Authority

Bank / Deposit-Taking Institution

Use this when a business claims it is a bank or accepts deposits from the public as part of the business of a bank. Registered banks are supervised by the Prudential Authority.

Check:Exact institution name · registered-bank status · official website/contact details
Check registered financial institutions ↗
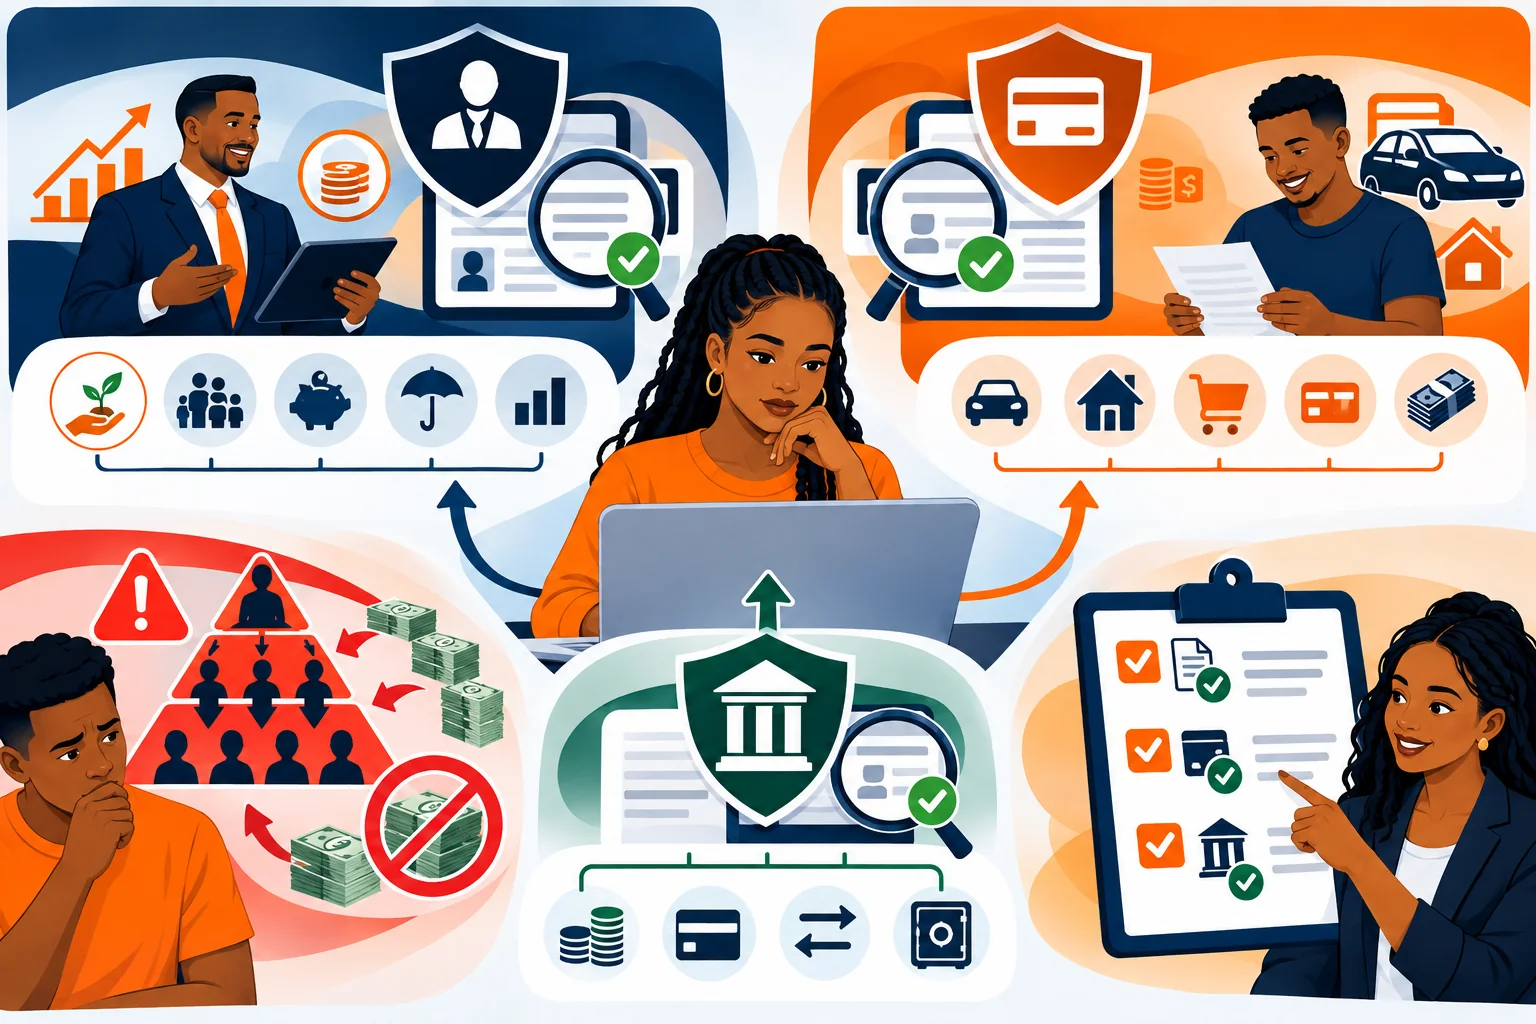
FSP vs credit provider: what is the difference?

They regulate different activities. One registration does not automatically cover the other.

FSP / FSCA

Advice & intermediation

An authorised FSP is licensed under the FAIS framework to render financial advice and/or intermediary services in relation to financial products.

Example: recommending or arranging an investment or insurance product.
≠
Credit Provider / NCR

Lending & consumer credit

A registered credit provider extends credit under the National Credit Act. The statutory registration threshold is nil (R0), so the registration requirement is not avoided merely because the lender is small.

Example: providing a personal loan, short-term loan or store credit.
A business may need more than one authorisation. If it carries on activities that fall under different regulatory regimes, check every relevant registration. Never assume an FSP number proves that a lender is NCR-registered, or that an NCRCP number authorises investment advice.

How to verify safely

Do not verify a provider using only documents or links supplied by the provider itself.

1

Search the official register yourself

Type the regulator's official web address or use the verified links on this page. Do not rely on a screenshot of a certificate.

2

Match the legal name and number

Check that the exact business/person you are dealing with matches the registered entity. Scammers can copy another firm's FSP or NCR number.

3

Check what the registration actually permits

For an FSP, confirm the authorisation is relevant to the product or service being offered. For a lender, confirm current NCR registration.

4

Verify contact details independently

Use the regulator's record and the institution's official website to confirm the phone number, email/domain and bank details before paying.

5

Stop if recruitment or guaranteed returns drive the offer

Recruitment-based returns, guaranteed high profits, pressure to bring in new members and difficulty withdrawing funds are major warning signs.

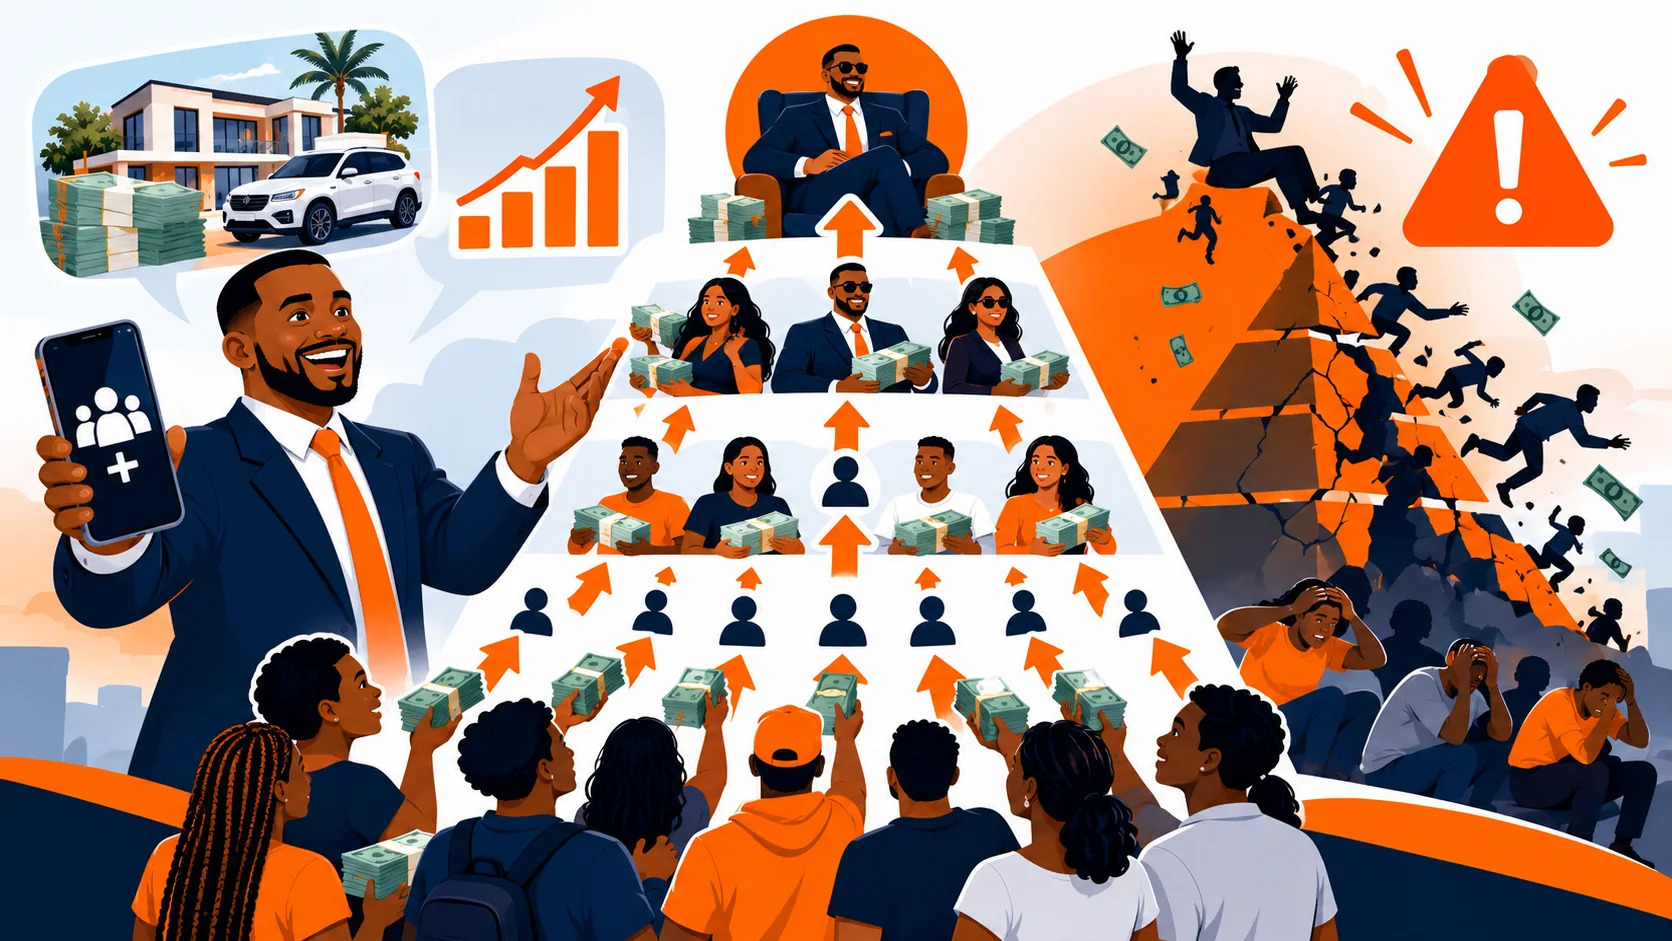
Illustration showing money flowing up a recruitment pyramid before the scheme collapses
Pyramid & Ponzi warning

New money should not be the business model.

SARB describes a pyramid scheme as requiring active participation and recruitment after an entry payment. In a Ponzi scheme, investors are generally passive while newer investors' money is used to pay earlier investors.

  • Pressure to recruit others to earn or unlock returns.
  • Returns that appear unusually high, fixed or guaranteed.
  • Little or no clear underlying business activity producing the returns.
  • Withdrawal delays, excuses or demands for another payment.
  • Claims that registration with CIPC alone makes the investment legitimate.
Advertisement